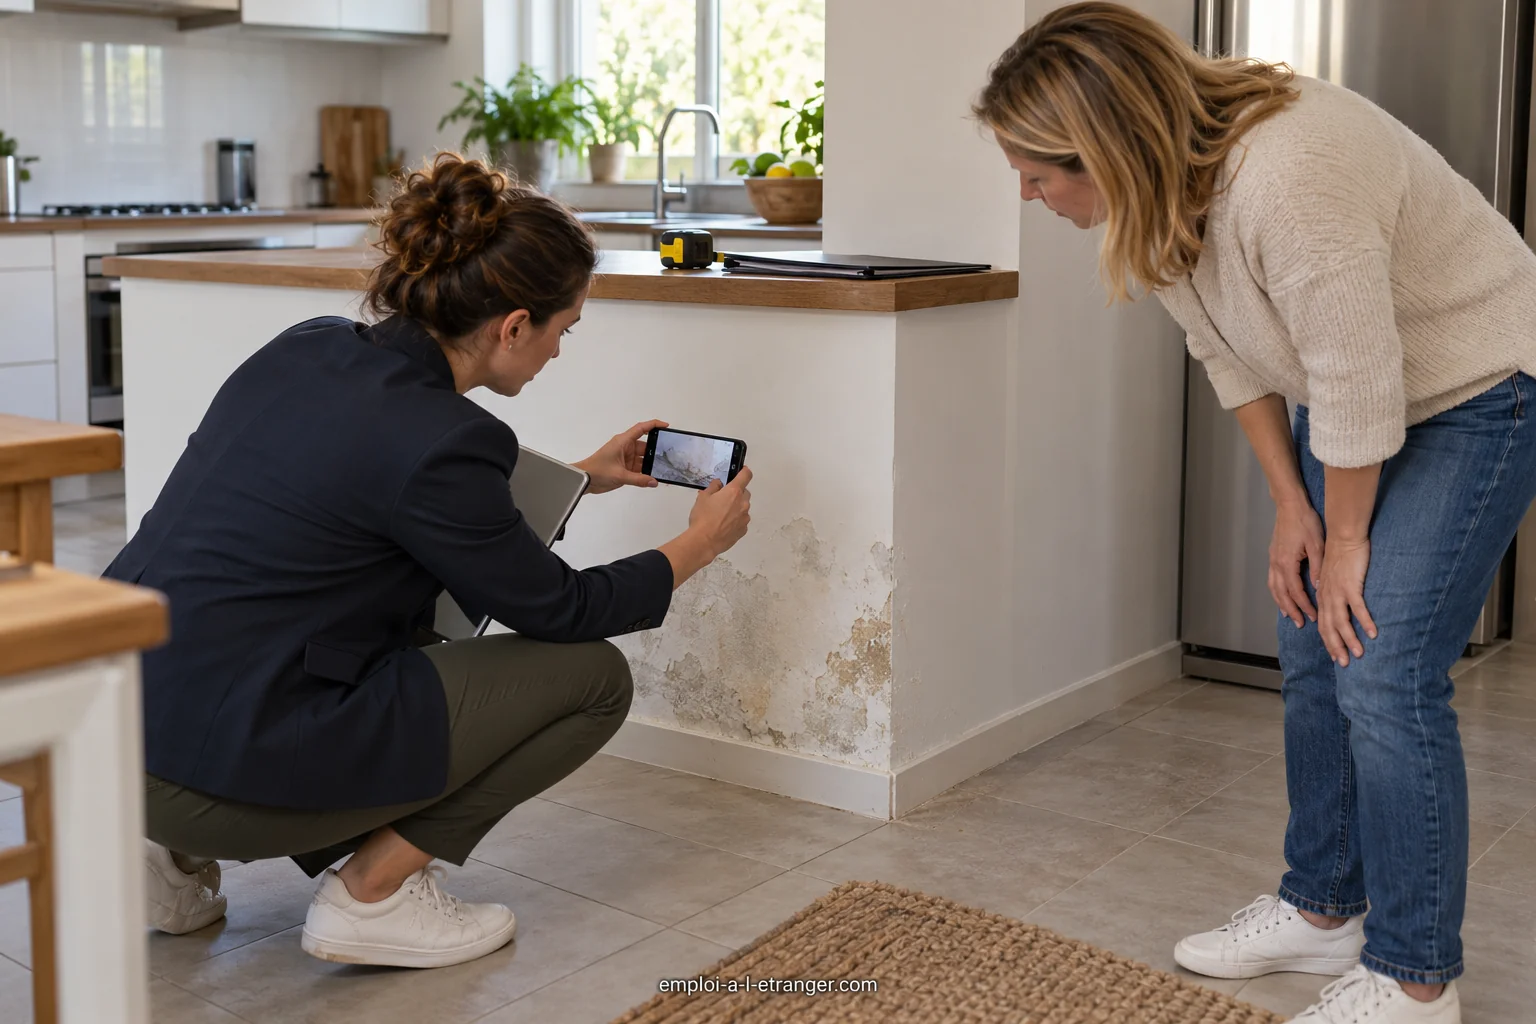
One job title, several claims handling careers
A claims handler can work in motor, home, health, liability, transport or commercial risks. Depending on the line, daily work differs: calls from private customers still in shock, technical analysis of bulky files, negotiation with law firms or loss adjusters.
In an application abroad, state the line of business and the type of files you handle well. An employer seeking a liability profile will not read a career centred on private water-damage claims in the same way. This precision saves you pointless interviews and saves the employer time.
- Insurance line handled
- Size and complexity of files
- Share of customer contact and analysis
- Level of settlement authority
Describing your role in a file without exposing policyholders
A recruiter wants to understand how you reason. Choose a typical, anonymised file: claim notified, cover checked, documents requested, exchange with the adjuster, settlement offer, discussion with the policyholder in case of disagreement. Show where your decision began and where it stopped.
This step-by-step presentation is better than a monthly volume of files, which varies a great deal with the nature of the claims. Also specify the limits of your authority: above what amount or level of complexity a superior signed off, because internal governance matters a lot abroad.
Cover, exclusions and deadlines: learning the local framework
Insurance contracts obey a law specific to each country, sometimes to each region. Definitions of fault, exclusions, notification deadlines, how the value to be paid is calculated, limitation periods: none of these can be deduced from a neighbouring market. A good handler knows they must relearn, and says so.
Ask at interview how the company trains newcomers: procedures manual, a buddy, regulatory training, access to a lawyer. Look also at the regulator or supervisory authority of the market concerned, whose publications explain insurers’ obligations towards policyholders.
Claims systems and organising complex files
Platforms for claims handling, tracking documents and communicating with policyholders vary from one insurer to another. Ask which tools you will use, how much automation exists and how simple and heavy files are shared out.
For complex files, find out whether specialist teams exist, whether external experts are used and how often portfolios are reviewed. A post where every difficult file lands with the same handler, without support, quickly degrades the quality of follow-up and your own wellbeing at work.
- Handling system and document tracking
- Split between simple and complex files
- Specialist teams and external experts
- Periodic portfolio reviews
Language of written and telephone exchanges
A claim is settled through precise letters. A badly chosen phrase may appear to commit the insurer or to refuse cover. Ask which language is used for letters to policyholders, whether templates exist and who reviews sensitive replies.
On the phone the demands are different: listening, clarity, rephrasing, handling emotion. If you work in a language that is not your own, offer a role-play at interview. You will show your real level, and you will judge in return how tolerant the team is of accents and mistakes.
Customer contact, technical analysis and negotiation: where is the balance?
Under one title sit posts very focused on customer relations, with many calls and satisfaction targets, and posts of technical analysis, with few calls but detailed reports. Others add negotiating settlements or recovering money from liable third parties.
Ask the approximate share of each activity and how performance is measured. If the focus is mostly on how fast files are closed, the quality of analysis may suffer. If satisfaction is what counts, firmness towards unjustified claims can become delicate.
Spotting employers and markets to apply in
Large groups such as AXA, Allianz or Zurich publish their international vacancies on their careers sites, with the country, the line of business and the languages asked for. Other recruitment goes through brokers, loss-adjusting firms, delegated claims administrators and assistance companies.
Choose a limited number of markets to go deep rather than scattering applications. For each country, note the regulator, the languages used, the diplomas or certifications common in insurance and the particularities of the claims market, for example frequent use of independent adjusters.
Contract, work permit and the first months
As with any move, check the contract, the place of work, the probationary period and the pay terms. If the employer is recruiting you from abroad, ask which work authorisation is needed and who starts the process; then verify the information with the country’s competent authority.
For the first months, ask for a gradual induction: simple files first, then increasing complexity, with a reference person available. You will gain accuracy, and the employer will limit the risk of a costly mistake on a badly calculated settlement.
Common mistakes made by claims handling candidates
The first mistake is to present claims handling as a purely administrative job. Recruiters look instead for someone who can decide, explain a refusal of cover tactfully and spot a suspicious file without accusing the policyholder. Your application should therefore contain at least one example of a difficult decision.
The second mistake is to promise instant mastery of local law. It is better to announce a learning method: reading the general terms, talking with a lawyer, having a senior review your first files. Finally, do not neglect discretion: talking about identifiable policyholders at interview ruins your credibility.
- A difficult decision explained without jargon
- A method for learning local law
- Discretion about policyholders
- Prepared questions about training
Frequently asked questions
Do I need an insurance qualification to become a claims handler abroad?
It depends on the market and the employer. Some countries value professional insurance certifications, others recruit mainly on experience and in-house training. Read the adverts carefully, ask the recruiter and check with the regulator or professional association of the target country.
Is my claims experience from home valued elsewhere?
Yes for the method: file analysis, dealing with the policyholder, following up with an adjuster. Less so for legal knowledge, which is specific to each market. Present what transfers, acknowledge what you will need to learn, and ask about the training planned to close the gap.
Can I move into loss adjusting or broking from claims handling?
It is a common path, but it depends on the qualifications required in each country and on employers’ needs. Ask recruiters about internal routes, funded training and the status of adjuster or broker, which is often regulated locally.
Is remote working common in this job abroad?
It exists for files handled in writing, but call teams or sensitive analysis may require presence in the office. If remote working is mentioned from a country other than the employer’s, ask about the social security and tax consequences before accepting, as they are not automatic.